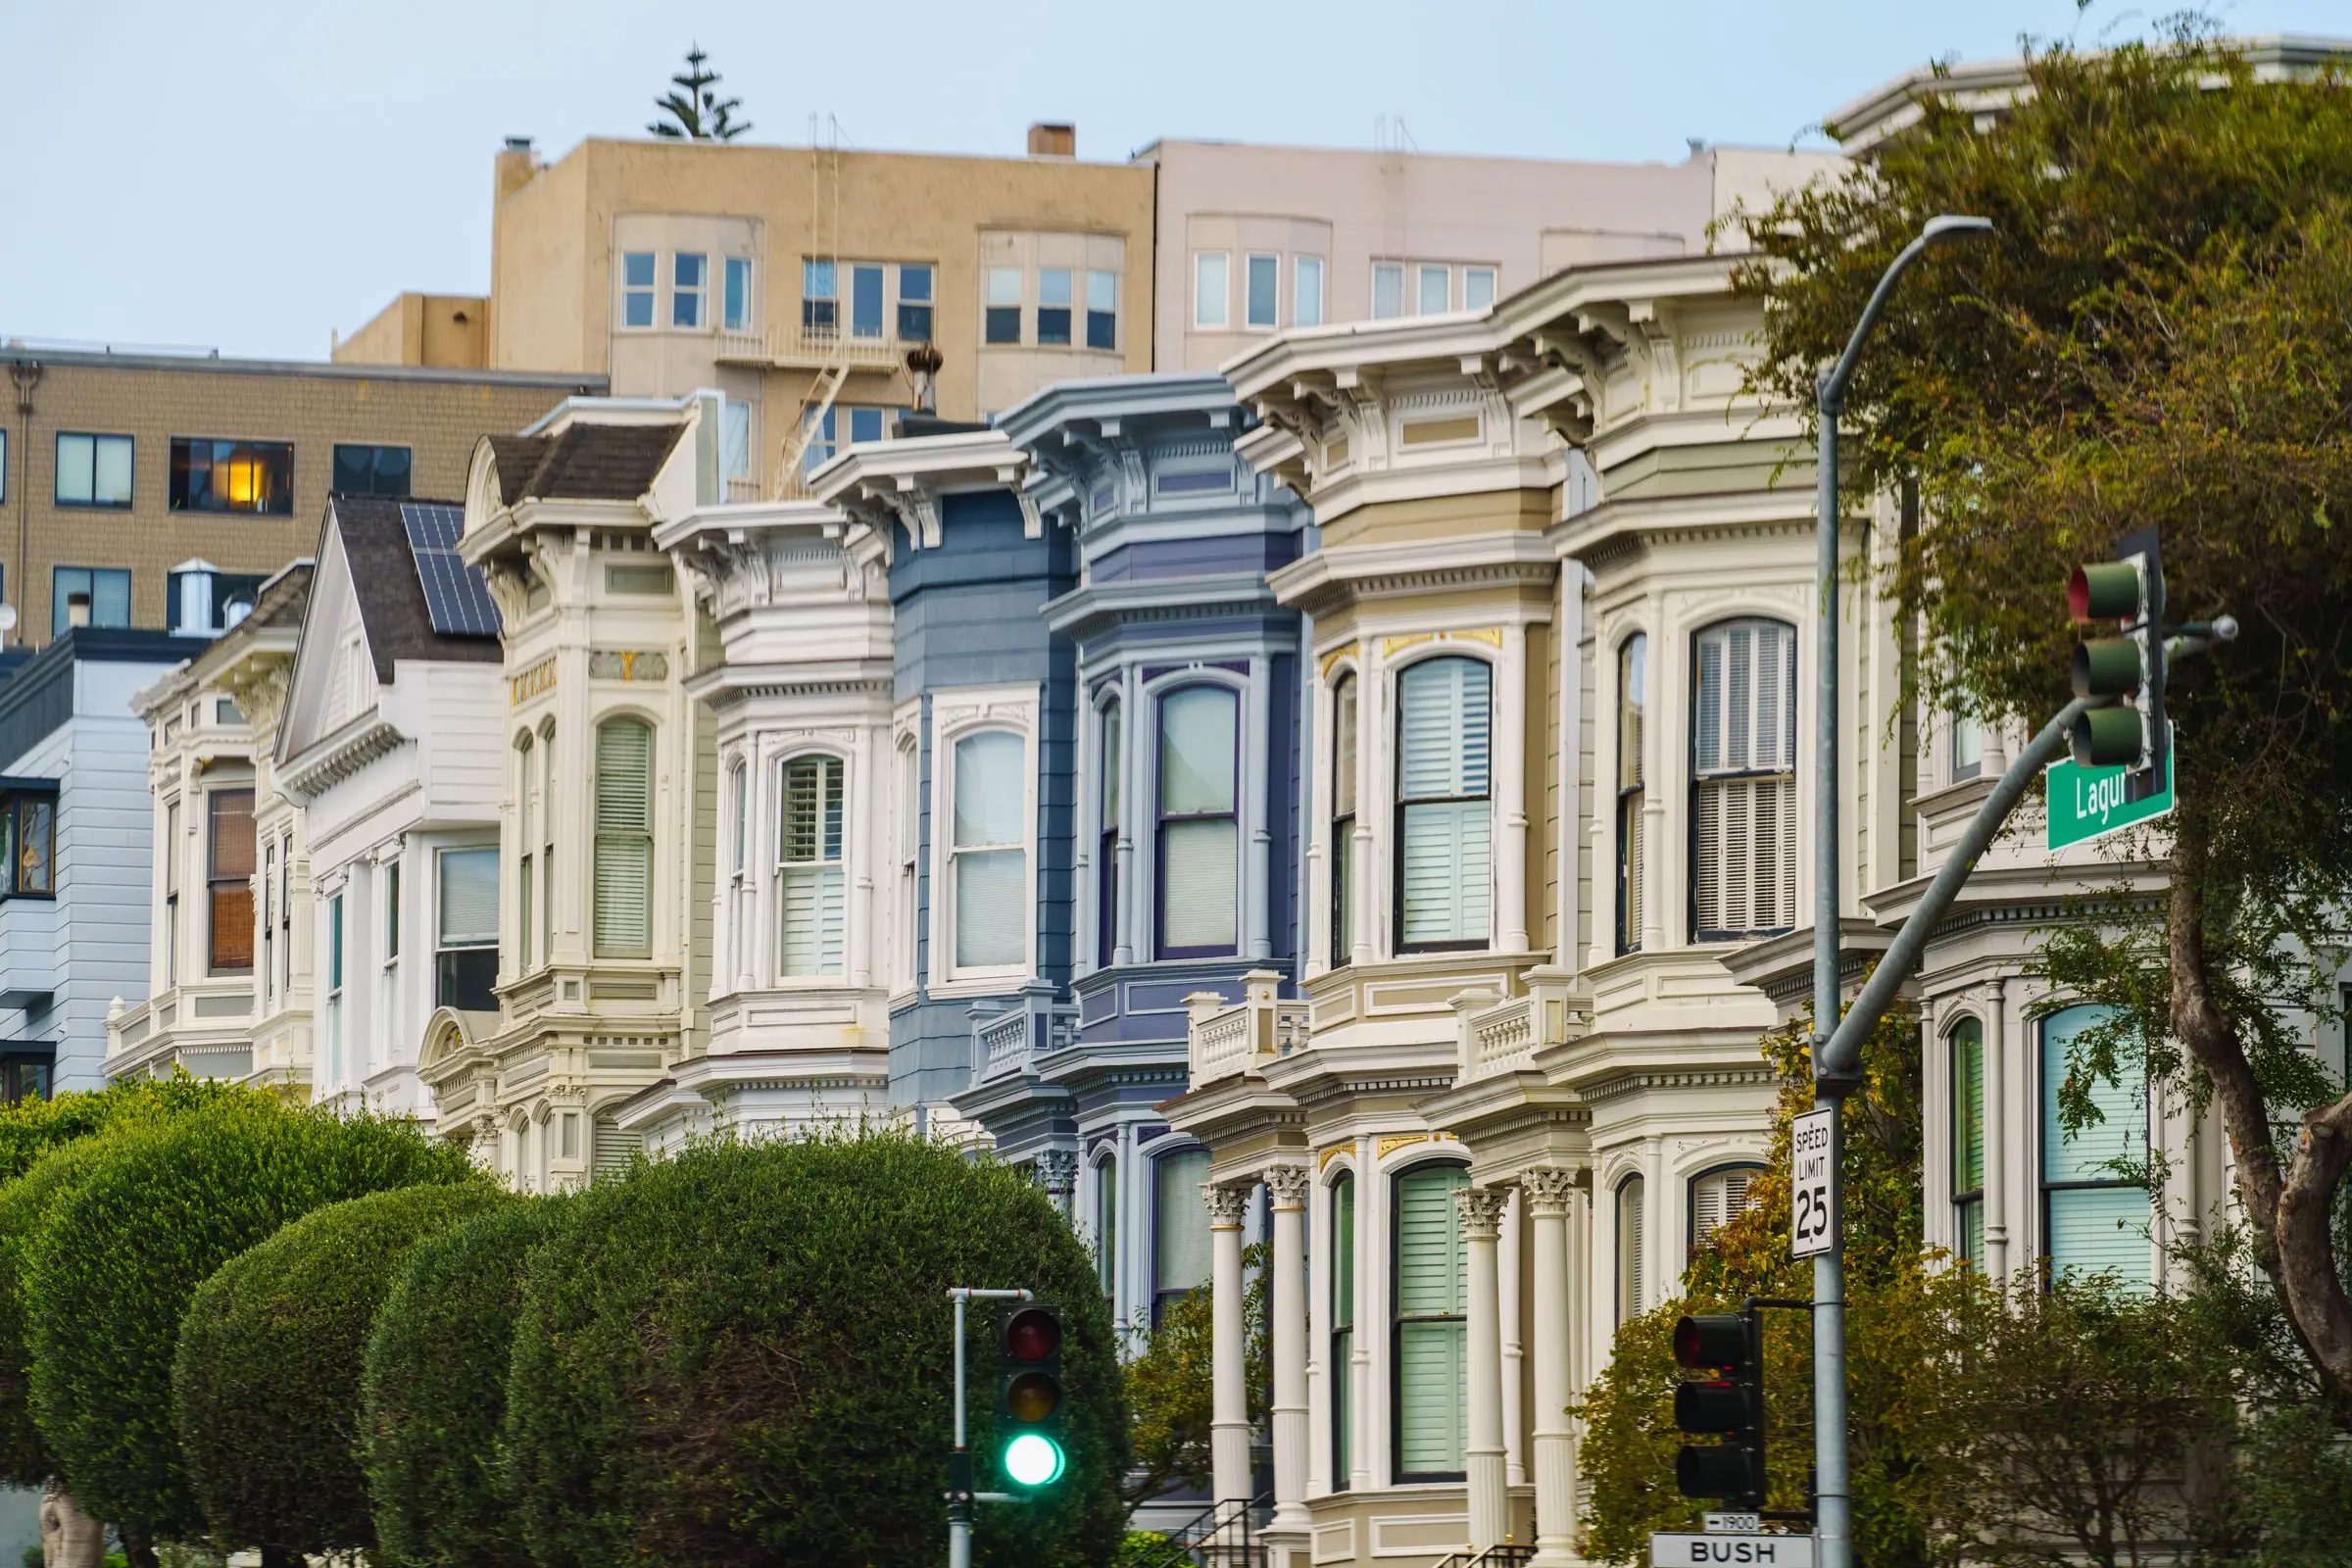
This chapter helps you figure out what kind of home you're actually looking at before you fall for the crown molding. San Francisco's housing goes back 150 years, and it's quirky: Victorians on brick foundations, Sunset houses with "bonus rooms" no permit ever approved, buildings that are legally one thing and used as another. The ownership structure, the building's age and its rent-control status will cost or save you more than any finish.
The short version
- Style tells you what usually breaks. Victorians and Edwardians (pre-1915) bring foundation, wiring and plumbing questions. 1920s–50s Marina-style and Doelger houses bring sand-soil, garage-level and unwarranted-unit questions.
- Condos: read the HOA's (homeowners association's) budget, reserve study, minutes and SB 326 balcony report. A lender can refuse the building (warrantability) even when it's happy with you.
- TICs (tenancy-in-common) sell at a discount because financing is niche, a little pricier and needs a bigger down payment, and because condo conversion is effectively frozen except for 2-unit buildings.
- 2–4 unit buildings are often rent-controlled. If you'd have to evict a tenant to live there (an owner move-in, or OMI, or an Ellis Act withdrawal), you're signing up for a slow, expensive legal process with strict rules. If you want to live there, look for a building that's already vacant, ask how it became vacant, and talk to a tenant-landlord attorney before you offer.
- Unwarranted units became much harder to remove under ordinances that took effect in fall 2025. Assume that downstairs in-law is permanent.
A field guide to SF house styles
Sellers market a house's style. Read it as a rough guide to what the house is made of, how it was built and what's likely to need work.
| Style | Built | Where you'll find it | Typical bones | What to check first |
|---|---|---|---|---|
| Victorian (Italianate, Stick/Eastlake, Queen Anne) | 1860s–1900s | Pac Heights, Alamo Sq, NoPa, Haight, Noe, Mission, Bernal, Duboce Triangle | Balloon or early platform framing, tall ceilings, often on brick or unreinforced foundations | Foundation, knob-and-tube wiring, galvanized supply lines, settled floors, unpermitted ground-floor rooms |
| Edwardian | ~1900s–1910s | Richmond, Cole Valley, Noe, Inner Sunset, Marina fringe | Similar systems to Victorians but with more practical layouts. Many "flats" buildings (2–3 units). | Same as Victorian, plus whether a "single-family" is legally 2 units (see the 3R report) |
| Marina-style / period revival | 1920s–30s | Marina, Sunset, Parkside, Excelsior | Stucco, Spanish/Mediterranean details, living space over the garage | Marina: bay fill and liquefaction. Everywhere else: garage-level conversions. |
| Doelger / tract houses | mid-1920s–1940s | Sunset, Parkside, Golden Gate Heights | Henry Doelger mass-built thousands on Sunset dunes, often "junior fives" (2BR/1BA over a 1-car garage) | Sand-soil foundations, salt-air corrosion near Ocean Beach, unwarranted downstairs units |
| Mid-century | 1950s–60s | Diamond Heights, Forest Hill/Miraloma, parts of the West of Twin Peaks, Glen Park | Post-and-beam, big glass, slab or hillside foundations | Hillside drainage and retaining walls, single-pane glazing, early-aluminum or ungrounded wiring |
| Modern / gut-rebuilt | 2000s–now | Noe, Eureka Valley, Pac Heights, Cow Hollow, Bernal | Often a new house inside a 1900s façade | Permit final sign-offs. A flipper's "fully permitted" claim is not the same as a finaled permit. |
A few terms from the table. Knob-and-tube is very old electrical wiring that insurers and inspectors flag. Liquefaction is when loose, wet soil (like bay fill) acts like liquid in a strong earthquake. The 3R report (Report of Residential Building Record) is the city's record of a property's legal use and number of units.
Nearly everything in this table predates 1978, so the federal lead-paint disclosure applies almost everywhere. Most single-family homes built over a garage are also effectively "soft-story" (a weak ground floor that can collapse in a quake), even though the city's mandatory retrofit program only covered 5+ unit buildings. If you're buying one, budget for a voluntary retrofit and get a quote from a seismic retrofit contractor →.
Condos: you're joining a small government
When you buy a condo, you own your unit outright plus a shared stake in the common areas (roof, lobby, hallways). An HOA runs the building and collects monthly dues. Most of the risk sits with the building, not your unit.
What to read in the HOA packet (the condo part of your disclosure review):
- Current budget and the most recent reserve study. What percent funded are reserves?
- Board minutes for the last 12–24 months. Search for 'assessment', 'leak', 'litigation', 'insurance', 'balcony'
- Any special assessments, levied or proposed
- Pending litigation, especially construction-defect suits against the developer
- Master insurance policy: does it cover earthquake? Has the premium jumped?
- SB 326 exterior-elevated-element (balcony) inspection report and any repair plan
- CC&Rs: rental caps, pet rules, renovation approval process
- Soft-story compliance if the building is wood-frame, 5+ units and pre-1978
The reserve study estimates what the building will need for big repairs and how much it has saved. The CC&Rs (covenants, conditions and restrictions) are the building's rulebook.
SB 326: balcony inspections with a deadline
California's SB 326 requires condo associations to have a licensed engineer or architect inspect a sample of exterior elevated elements: wood-supported balconies, decks, stairs and walkways more than 6 feet above ground. The first inspection was due January 1, 2025, then every 9 years alongside the reserve study. The 2024 extension (AB 2579) applied only to apartment buildings under SB 721, not to HOAs. A building that hasn't done its SB 326 inspection is out of compliance. A building that has done one may have found expensive problems. Either way, ask for the report.
Warrantability: when the lender says no to the building
Lenders review the building as well as you. A building can become non-warrantable (one many lenders won't finance) because of litigation, a high share of investor-owned units, a big commercial component, thin reserves, a single entity owning many units, or a weak master insurance policy. That matters most for conforming loans (up to $1,249,125 in SF in 2026). Most SF condo buyers above that line use jumbo lenders who keep loans on their own books, and they apply their own building rules, which may be stricter or looser. Ask your lender to pre-clear the building before your offer date, not during escrow. For more, see Mortgages.
New-construction towers
Rincon Hill, South Beach, Transbay and Mission Bay have the city's glass towers: amenities, views, and no old wiring. The trade-offs:
- HOA dues often run four figures a month.
- Mello-Roos / CFD special taxes apply in master-planned districts. A CFD (community facilities district) adds a yearly tax to pay for local infrastructure. Examples include Transbay CFD 2014-1, Mission Bay, Mission Rock, Hunters Point Shipyard and Treasure Island. In FY 2020-21, Transbay's base special tax was reported at about $6.20–$9.69 per sq ft a year, depending on building height. Ask for the current figure, because it shows up on the property tax bill, not in the HOA dues.
- Downtown condo prices have lagged the rest of the city. That's the value opportunity, and also why resale can be slow.
- Millennium Tower (301 Mission) is the best-known example of building problems showing up in prices. Its perimeter-pile fix finished in 2023 and the sinking reportedly stopped, but sales from 2023 to mid-2026 were reported at a median of about $1.2M (~$815/sq ft), and some units reportedly resold at 20–50% below their earlier prices. A building's history affects the price of every unit in it.
TICs: why they cost less
In a tenancy-in-common, you and your co-owners each own a fractional share of the entire building, plus the exclusive right to live in your unit under a TIC agreement. It's a very San Francisco workaround, born from decades of limits on turning apartments into condos.
Why TICs are cheaper than comparable condos:
- Financing is niche. Each owner gets a fractional TIC loan from a short list of lenders, among them Sterling Bank & Trust, NCB, Bank of Marin, Redwood Credit Union, Bank of San Francisco, and JPMorgan (via First Republic). Rates reportedly run about 0.5–1.25 points above comparable condo loans, and down payments are typically 15–25%+. NCB has offered 30-year fixed TIC loans. Older TICs may still carry a single group loan, which makes every owner responsible if any other owner defaults. Avoid those unless you understand the risk.
- The rules come from a contract. Your neighbors are your co-owners. The TIC agreement covers defaults, sales, renovations, and what happens when someone stops paying. Have a TIC attorney read it.
- Conversion is mostly frozen. See below.
Can a TIC become a condo? (as of October 2026)
- The condo conversion lottery has been suspended for years. The Expedited Conversion Program ran from 2013 to 2020 and has been on hiatus since. Its projected return "in 2024, 2025 or 2026" has not happened, according to the most recent sources we found.
- 2-unit buildings can still convert through the owner-occupancy bypass. Both units must be owner-occupied for one year by separate owners who each hold at least 25%, and the building needs a clean eviction history. It's reportedly an administrative process of about 6–12 months.
- 3–6 unit TICs can't convert unless the city reactivates the lottery. Price them as permanent TICs and treat any conversion as a long shot.
- Eviction history matters. A past Ellis Act or certain owner-move-in evictions can bar conversion and limit future owner move-ins.
2–4 unit buildings and rent control
Multi-unit buildings are appealing: live in one unit, rent out the rest, and use the higher conforming loan limits ($1,599,375 for 2 units, up to $2,402,625 for 4). The catch is the SF Rent Ordinance.
| Rule | What it means for you |
|---|---|
| SF Rent Ordinance | Generally covers units in buildings with a first certificate of occupancy on or before June 13, 1979. The allowable annual increase is 1.6% for Mar 1 2026–Feb 28 2027. |
| Costa-Hawkins (state) | Exempts single-family homes, most condos, and buildings with a CO after Feb 1, 1995 from local rent caps, and allows vacancy decontrol. Just-cause eviction protections can still apply. |
| Owner Move-In (OMI) | You (or a qualifying relative) must move in in good faith for 36 continuous months. Protected tenants (seniors, disabled, catastrophically ill, families with school-age children) can block or limit an OMI. Relocation for notices served Mar 2026–Feb 2027 is $8,245 per tenant, up to $24,733 per unit, plus $5,497 for each elderly or disabled tenant or household with minor children. |
| Ellis Act | Withdraws every unit from the rental market. Relocation is $11,110.05 per tenant, up to $33,330.13 per unit, plus $7,443.90 per elderly or disabled tenant. It triggers long re-rental restrictions and condo-conversion bars. |
A certificate of occupancy (CO) is the city's sign-off that a building is ready to live in. Vacancy decontrol means rent can reset to market when a tenant moves out. Source for the rates: sf.gov. OMI ownership-percentage thresholds and the restrictions in TIC buildings get complicated. Confirm them with the Rent Board or a tenant-landlord attorney before relying on an OMI.
A few practical rules:
- Prefer a building that's already vacant. Buying a tenant-occupied building to live in it is slow, expensive and legally risky. Ask how any vacant unit became vacant: a recent OMI, Ellis Act withdrawal or tenant buyout can carry restrictions that pass to the next owner, and buyout agreements have to be filed with the Rent Board.
- Tenants keep their rights when a building sells. Pressuring a tenant to leave, cutting services or refusing repairs is unlawful harassment under the Rent Ordinance. Any plan that depends on a tenant leaving belongs with a tenant-landlord attorney before you make an offer.
- If tenants stay, get estoppel certificates (signed confirmations of rent, deposit and lease terms) and the unit's Rent Board history.
- The city's mandatory soft-story program covers 5+ units only. A 3-unit Edwardian over garages is outside it but just as wobbly.
Unwarranted units: the in-law you can't get rid of
"Junior five plus in-law" is a classic Sunset, Richmond, Excelsior and Bernal listing. The downstairs unit often has no permits, which makes it an unauthorized dwelling unit (UDU).
San Francisco has steadily shifted from tolerating UDUs to protecting them:
- Ordinances 240803 / 250798 took effect in fall 2025. Sources date the first one to September 2025, and one practitioner source gives October 5, 2025 for the package. Planning now reviews any project that might involve a UDU, triggered by permits touching kitchens, bathrooms, doors or stairs in that space, or by enforcement. If Planning finds a UDU, legalization is generally mandatory. Removal requires Planning Commission approval, which practitioners say is almost never granted.
- For single-family owners, removal is limited to cases where the owner lives in the main unit, the UDU hasn't been rented in the last 10 years (except to a close relative), and the owner commits to stay for 3 years and accept Rent Ordinance coverage.
- Unauthorized removal can draw fines of up to $250,000 per unit, as reported.
- Legalization under the city's program (Planning Code §207.3) often costs $100k+, because of fire separation, ceiling height, exits and sometimes sprinklers.
- A tenant in an unwarranted unit can still have rent-control and eviction protections, and in some cases may be able to claim refunds of rent paid for an illegal unit. If an in-law unit is occupied, have a tenant-landlord attorney review it before you buy.
ADUs: the legal version
Accessory dwelling units, or ADUs (garage conversions, backyard cottages, units carved from existing space), are broadly allowed in SF. Under a July 2025 SF law implementing state AB 1033, qualifying ADUs can be sold separately as condos. For lots with room, that's a real change in what the property could be worth. The Family Zoning Plan passed in December 2025 also raised allowed heights and densities along many west- and north-side corridors, though it faces lawsuits and its effect on values is unclear.
If an ADU is part of your plan, check feasibility before you buy: lot coverage, rear-yard setbacks, ceiling height at the garage level, and the sewer lateral (the pipe from the house to the city sewer). Then talk to an ADU builder → who has finaled permits in your neighborhood. Our contractor index shows you who that is. More in Renovating.
Co-ops, briefly
These are mostly pre-war Nob Hill, Russian Hill and Pac Heights buildings. You buy shares plus a proprietary lease (a long-term right to your unit), pass a board review (full financials, sometimes an interview), and may face 20–50% minimum down or all-cash rules, plus rental restrictions. Share loans come from a small set of lenders. The buildings are beautiful; the ownership structure takes some getting used to.
How the types compare
| Type | Financing difficulty | Typical risk concentration | Resale liquidity |
|---|---|---|---|
| Single-family house | Easiest (jumbo or conforming) | Structure, permits, foundation | Highest. Houses are where the 2026 bidding wars are. |
| Condo (small building) | Easy if warrantable | HOA finances, special assessments | High |
| Condo (tower) | Easy, but check CFD and building review | HOA dues, CFD taxes, building reputation | Medium. Downtown has lagged. |
| TIC | Niche lenders, +0.5–1.25 pts, 15–25%+ down | Co-owners, TIC agreement | Medium-low |
| 2–4 units | Conforming limits up to $2.4M | Tenants, rent control | Medium |
| Co-op | Board approval, high down payments | Board, building | Low |
Next: once you know the type, pick the place in Neighborhoods by budget.
Sources & verification›
- Current rates: rent increase, relocation — City and County of San Francisco, 2026
- Bringing UDUs to Light: Ordinances 240803 / 250798 — MyPropertyAtlas, 2025
- Unwarranted Units in San Francisco: Legalize It, Don't Remove It — MyPropertyAtlas, 2025
- SF erects new barriers to removing unwarranted units — Bornstein Law
- Legalization fact sheet — SF Planning
- SF ADUs can now be sold as condos — Mission Local, Jul 2025
- SF Family Zoning Plan — SF Planning
- San Francisco's condo conversion lottery system — Andy Sirkin
- Understanding TIC-condo conversion in San Francisco — Prism Group
- More TIC lender choices — Inside SF RE
- TIC loans — Redwood Credit Union
- SB 326 for HOAs after January 2026 — Bay Legal PC
- Is the SB 326 deadline in 2026? AB 2579 explained — Bay Cities Construction
- Sunset District tract history — Western Neighborhoods Project
- 301 Mission St sales history — Ownify, 2026
- Transbay CFD administrative report FY 2020-21 — SF Controller
- SF condo market report, spring 2026 — Inside SF RE, Jun 2026
- OpenAI surges past 1M sf of offices in SF — The Real Deal, Mar 2026
- Buying a co-op in San Francisco — McMullen